A fresh debate has erupted over India’s most celebrated digital payment success story, after BharatPe co-founder Ashneer Grover strongly criticized the possibility of new charges being levied on UPI (Unified Payments Interface) transactions, calling any such move nothing more than a disguised tax on Indian citizens.
What Sparked the Debate
The controversy follows a government gazette notification dated September 14, 2026, which clarified that no bank or payment system provider can impose any direct or indirect charge on UPI transactions up to ₹2,000, or on RuPay debit card payments. However, the notification left the door open for potential charges on larger transactions — particularly those made by merchants — sparking concern over what this could mean for the broader payment ecosystem.
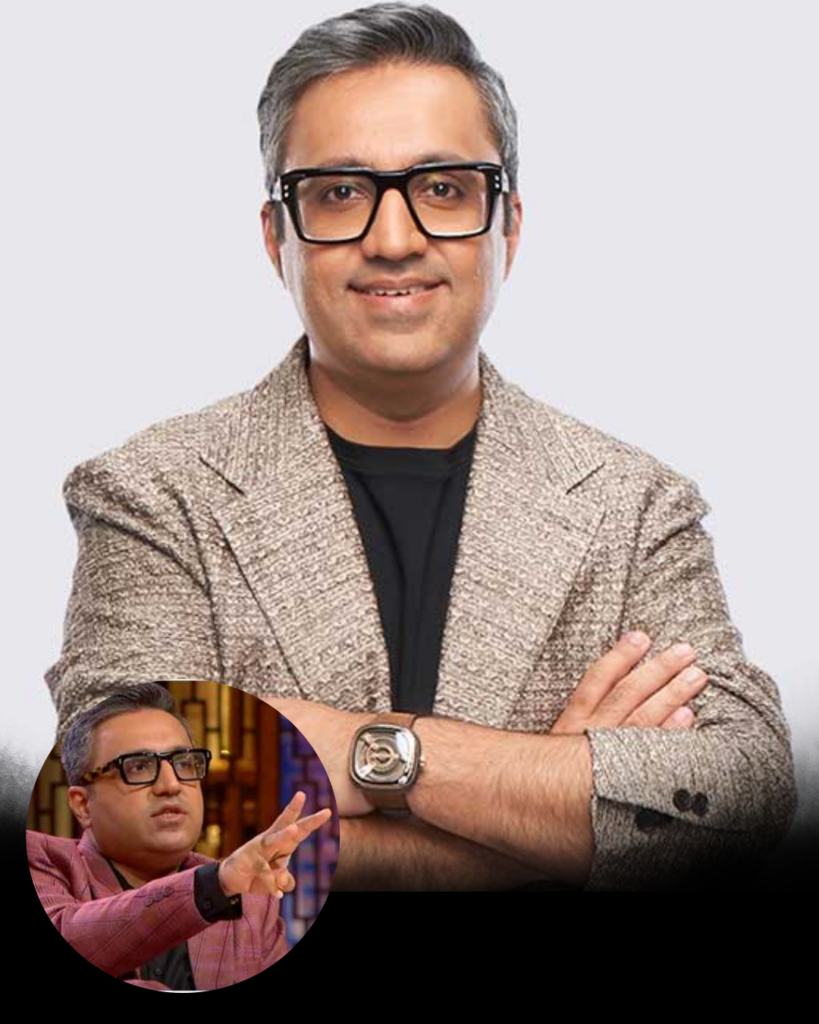
Grover’s Argument
Speaking to CNN-News18 and in a detailed post on social media platform X, Grover argued that introducing fees on a payment system that has already proven wildly successful made little sense. He questioned why the government needed to interfere with something that works, and specifically took issue with where the ₹2,000 threshold was drawn — pointing out that transactions above that amount make up only about 4% of UPI’s total transaction volume by count, but account for a much larger share of transaction value.
Read More: UPI’s Zero-MDR Era May No Longer Be Permanent: What the New Bill Means for Users and Merchants
To back his argument, Grover cited hard numbers: the National Payments Corporation of India (NPCI), which operates UPI, reported a pre-tax surplus of around ₹1,888 crore (approximately $200 million). He also referenced the Reserve Bank of India’s surplus transfer to the government, cited at around ₹2.87 lakh crore, along with the financial strength of listed banks — arguing that no single stakeholder in the ecosystem is genuinely “losing money” because of UPI’s zero-fee model for consumers.
Grover further highlighted that India’s traditional cash infrastructure — including ATMs and cash logistics — costs the banking system an estimated ₹30,500 crore annually (roughly $3 billion). His argument: if cost optimization is truly the goal, banks should be incentivized to reduce reliance on cash infrastructure and lean further into digital rails like UPI, rather than taxing the very system that reduces those costs.
In his own words on X: “Any levy on UPI is just tax collection. UPI is the one scientific achievement of India everyone acknowledges — par ab tax ki bali chadhegi” (but now it will be sacrificed to tax).
Government’s Response
The Finance Ministry has since clarified that UPI will remain completely free for consumers, and that person-to-person (P2P) transactions will continue to carry zero charges. Any future Merchant Discount Rate (MDR) would be limited strictly to specified merchant transactions above a set threshold and would reportedly be “nominal” rather than substantial.
The Bigger Picture
Grover also warned that poorly calibrated charges on larger transactions could risk pushing India back toward a cash-driven economy — undermining years of progress toward digital financial inclusion. As the notification’s finer details continue to be debated, Grover’s remarks have reignited a broader public conversation about transparency, subsidy structures, and who ultimately bears the cost of running India’s payment infrastructure.
The final policy stance on merchant-side UPI charges is still awaited, with further clarity expected in the coming weeks.